Share this article
The Taming of Chance – How the World Became Random
U ntil the nineteenth century, science assumed the world was governed by hidden, deterministic causes, with probability used only where those causes couldn't yet be explained. Then something shifted: chance stopped being a symptom of ignorance and became the very nature of things — first in physics, then, with far greater consequences, in the description of human beings and markets.
SYSTEMIC.risk
MODEL.risk
The Probabilistic View of the World — The Taming of Chance
As late as the nineteenth century, the deterministic description of the world still prevailed. Laplace (1814) held that the course of phenomena resulted from their deterministic mechanics. Science had a single ideal of explanation — find the causes, derive the trajectory, predict. This way of describing the world was regarded as the sole true one. Maxwell (1860) and Boltzmann (1872), who studied gas and its molecules, introduced the so-called macroscopic mode of describing phenomena. At the time, however, they did not call into question the nature of gas behavior — a certain mechanics of the natural world. They merely proposed a different conceptual map for describing it: a statistical description of gas, by means of a probability distribution. From that point on, we speak of two levels of description: the microscopic (trajectories, causes, mechanics), and the macroscopic (distributions, probabilities, statistics).
Meanwhile, shortly afterward — likewise in the nineteenth century — something occurred that Hacking (1990) termed the "taming of chance." Chance ceased to be regarded merely as a facet of ignorance; it acquired autonomy, as the very essence of the matter, rather than as a mode of description. The natural world was now, in itself, random, by its very nature of existence. This, in turn, opened the door to statistical tools grounded in probability calculus — already fairly well developed by that time — as fully legitimate forms of description, consistent with the very nature of things.
Download full version of article
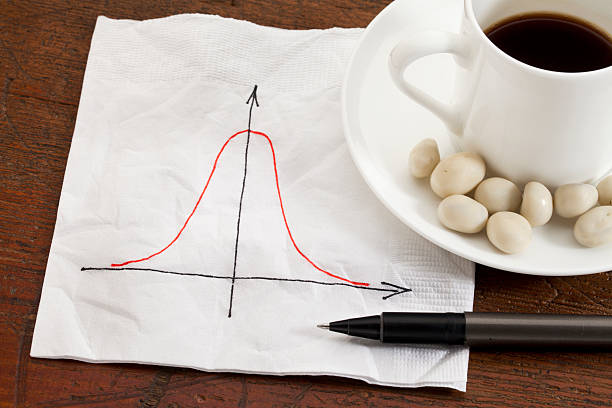
DownloadThe process of "taming chance" likewise began within the domain of socio-economic phe-nomena. Quetelet, in the 1840s (Hacking, 1990), was the first to transfer the curve of measurement error (as used in astronomy) onto human and societal characteristics. Quetelet applied the normal distribution to describe human traits, and developed the concept of the "average man." In doing so, he inaugurated probabilistic thinking within the social sciences. The mean for a society, its distribution, ceased to be merely a possible way of viewing a population. They came to be treated as a reflection of the laws of nature governing society. This line of thought was developed further by Galton (1889), and its mathematical formalization was undertaken by Karl Pearson (1896).
In insurance, randomness as the very nature of things was already being considered in the eighteenth century by Lambert (1772), who proposed a curve describing mortality, which helped in determining an adequate insurance rate. In the modeling of rare events and natural catastrophes, probabilistic ideas were later developed in succession by the researchers — Fuller, Hazen, Foster, and Gumbel — the fruit of whose work were the two Extreme Value Theories, I and II. In economics, meanwhile, the key step was taken by Bachelier (1900), who, in 1900, applied Brownian motion — known today as the random walk process — to the description of stock prices. Bachelier, forgotten for the next fifty years, laid the foundations for the concept of the randomness of value changes as a generic feature of this process. Norbert Wiener (1923), in the 1920s, gave Brownian motion rigorous mathematical foundations (the Wiener process). Paul Samuelson (1965) initiated the rapid development of theories built on this founding axiom, and it was on this very assumption that all subsequent theories were built: Black-Scholes (1973), Merton (1974), Vasicek (1987), J.P. Morgan (VaR) (1996), and so on — theories that constitute the philosophical foundation of contemporary risk management methodologies. The implementation of catastrophe modeling within the world of economics was, in turn, undertaken by, among others, Embrechts (1997).
In this way, ideas that had originally been intended merely as an alternative form of describing the world became integrated with that world, and came to constitute its very constitu-tion. The world became random, and, if so, the natural way of describing the world became the very science that concerns itself with randomness — that is, probability theory, particularly in its mature form, following the sanctioning, in 1933, of Kolmogorov's axioms (1933).
Instrumentalism and Pragmatism
The application of statistical tools to the description of phenomena has not always taken the same form. One can approach the matter in a mechanistic spirit, seeking real, structural justifications for the shapes of probability distributions — as did Fisher (1918). One can, alternatively, adopt an instrumentalist approach, as did Karl Pearson (1892), and, later, Neyman (1957), who lent this position methodological rigor in his concept of inductive behavior.
Karl Pearson was a positivist in the philosophical sense. He maintained that science does not discover reality; science constructs economical descriptions of phenomena. Scientific theo-ries, in his view, are not claims about reality, but tools for prediction and for organizing expe-rience. A theory does not describe what the world is like. A theory either works or it does not — it is either useful or it is not. Formulas are shorthand for thought, not descriptions of deep structure. For Pearson, a distribution was a curve fitted to the data. The question "why do the data take this shape?" was, for him, an improper question — a metaphysical one, not a scientific one.
This idea was developed further by Friedman (1953). He argued that the only proper test of a hypothesis's correctness is a comparison of its predictions against experience, and that truly important and significant hypotheses have assumptions that may, in fact, be strikingly inaccurate descriptions of reality. Scientific theories are simplifications. Always. The map is not the territory. The model is not reality. Were a model as complex as reality itself, it would be useless.
This particular formulation of thought had its consequences. Before Friedman, one could question a model's assumptions by arguing that they were not grounded in the real mechanics of reality. After Friedman, however, one could respond: I am not interested in whether the assumptions are realistic. I am interested in whether the model predicts well. That is all. An intellectual shield was thus created, one that protected models from criticism directed at their foundations. ■
Maciej Buczak
Risk management professional with 8+ years validating financial models in banking, currently teaching risk management and econometrics in Warsaw. His research questions the paradigmatic foundations of financial risk architecture — from VaR to AMA and IRB — drawing on extreme value theory.
References Academic sources cited throughout this article — click to expand the full list
Bachelier, L. (1900), Théorie de la spéculation, Annales scientifiques de l'École Normale Supérieure, 3e série, 17, pp. 21-86. English translation: Bachelier, L. (1964), Theory of Speculation, in: P.H. Cootner (ed.), The Random Character of Stock Market Prices, pp. 17-78, MIT Press, Cambridge MA.
Black, F., Scholes, M. (1973), The Pricing of Options and Corporate Liabilities, Journal of Political Economy, Vol. 81, No. 3, pp. 637-654.
Embrechts, P., Klüppelberg, C., Mikosch, T. (1997), Modelling Extremal Events for Insurance and Finance, Springer-Verlag, Berlin.
Fisher, R.A. (1918), The correlation between relatives on the supposition of Mendelian inheritance, Transactions of the Royal Society of Edinburgh, 52, pp. 399-433.
Friedman, M. (1953), The methodology of positive economics, in: Essays in Positive Economics, pp. 3-43, University of Chicago Press, Chicago.
Galton, F. (1889), Natural Inheritance, Macmillan, London.
Hacking, I. (1990), The Taming of Chance, Cambridge University Press, Cambridge.
J.P. Morgan/Reuters (1996), RiskMetrics™ – Technical Document, Fourth Edition, Longerstaey, J., Spencer, M., Morgan Guaranty Trust Company and Reuters Ltd., New York, December 17, 1996.
Kolmogorov, A.N. (1933), Grundbegriffe der Wahrscheinlichkeitsrechnung, Springer, Berlin.
Lambert, J.H. (1772), Anmerkungen über die Sterblichkeit, Todtenlisten, Geburthen und Ehen, in: Beyträge zum Gebrauche der Mathematik und deren Anwendung, Tl. 3, pp. 476-569, Berlin.
Laplace, P.S. (1814), Essai philosophique sur les probabilités, Courcier, Paris. English translation: Laplace, P.S. (1902), A Philosophical Essay on Probabilities (F.W. Truscott, F.L. Emory, trans.), John Wiley & Sons, New York.
Maxwell, J.C. (1860), Illustrations of the dynamical theory of gases. Part I, On the motions and collisions of perfectly elastic spheres, The London, Edinburgh, and Dublin Philosophical Magazine and Journal of Science, 19, pp. 19-32.
Merton, R.C. (1974), On the Pricing of Corporate Debt: The Risk Structure of Interest Rates, Journal of Finance, Vol. 29, No. 2, pp. 449-470.
Neyman, J. (1957), "Inductive behavior" as a basic concept of philosophy of science, Revue de l'Institut International de Statistique, 25(1/3), pp. 7-22.
Pearson, K. (1896), Mathematical contributions to the theory of evolution, III. Regression, heredity, and panmixia, Philosophical Transactions of the Royal Society of London, Series A, 187, pp. 253-318.
Pearson, K. (1892), The Grammar of Science, Walter Scott, London.
Samuelson, P.A. (1965), Proof that properly anticipated prices fluctuate randomly, Industrial Management Review, 6(2), pp. 41-49.
Vasicek, O.A. (1987), Probability of Loss on Loan Portfolio, Working Paper, KMV Corporation, San Francisco.
Wiener, N. (1923), Differential Space, Journal of Mathematics and Physics, Vol. 2, No. 1-4, pp. 131-174.
Reader Discussion
Share
your thoughts
Tip: Choose the category that best describes your comment. This may help other readers. See more